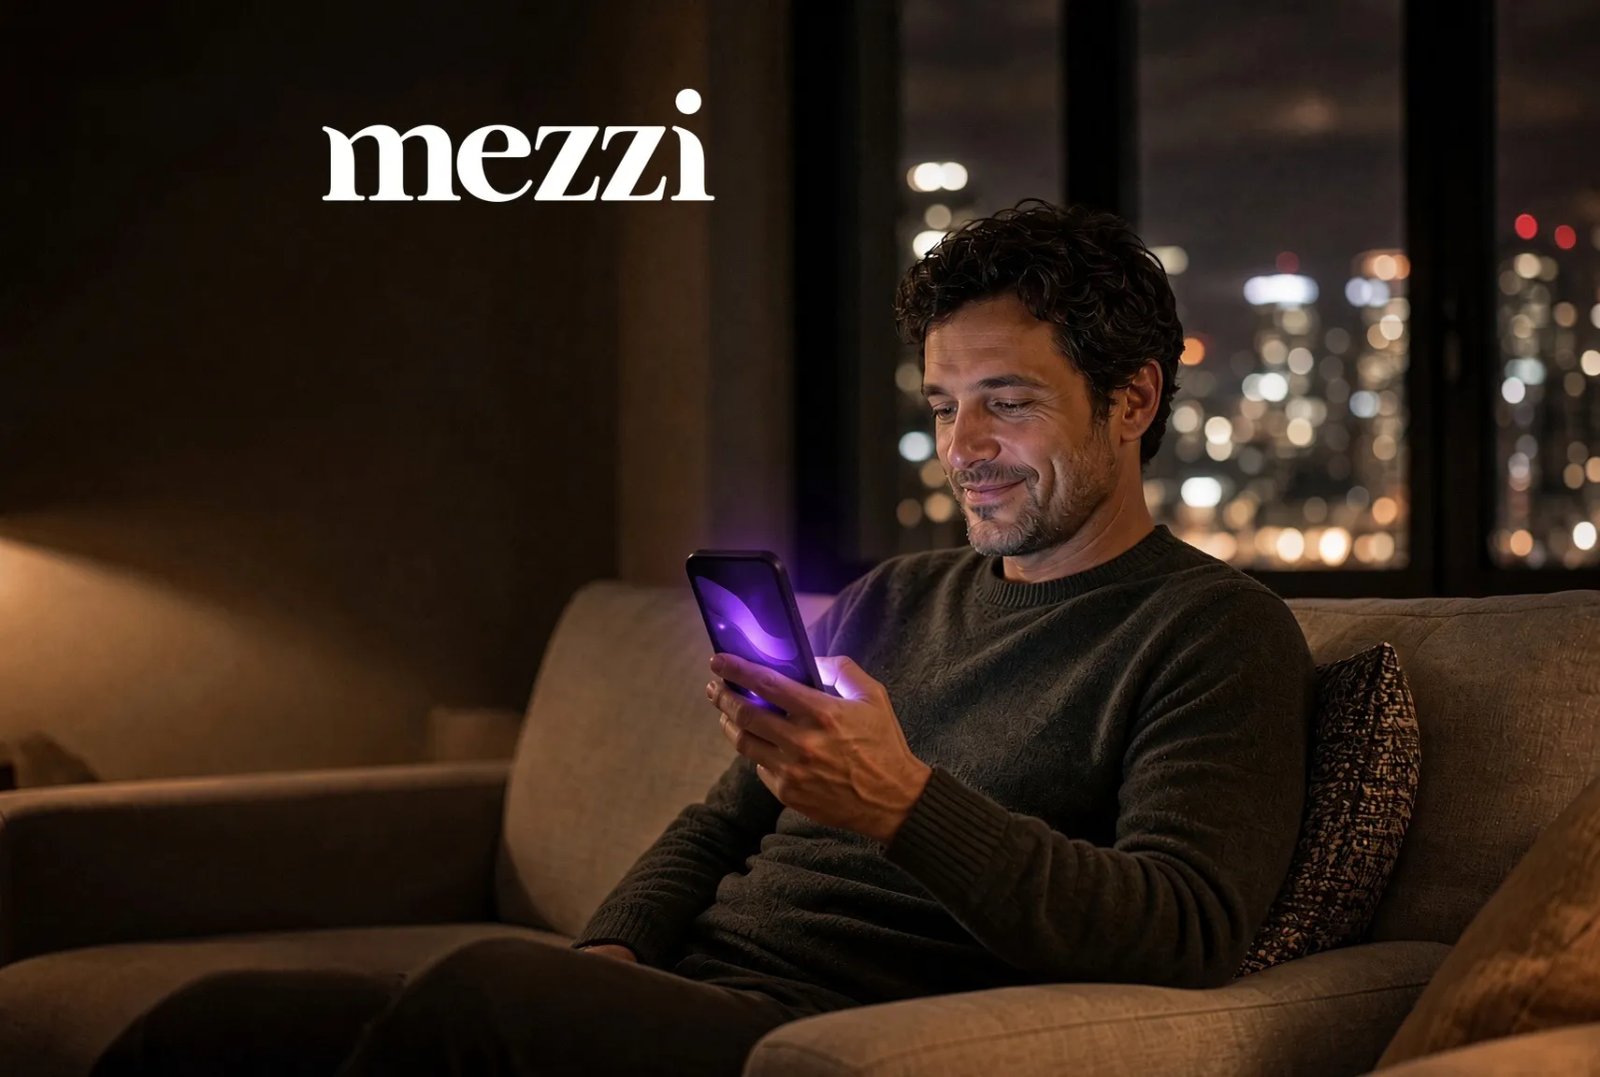
Increasingly complex financial landscapes are pushing individuals to seek more sophisticated management tools. Mezzi, an artificial intelligence-driven financial advisor, has emerged as a promising solution for users looking to streamline their investment and retirement planning processes.
Mezzi offers a unique conversational interface that allows users to ask specific questions about their portfolios at any time. This interactive component eliminates the barriers often faced with conventional advisors, such as awkward emails or waiting for responses. Additionally, Mezzi proactively identifies financial opportunities, such as tax-loss harvesting or fund adjustments, thereby enhancing a user’s financial strategy without needing to be prompted.
A recent study from NYU Stern found that portfolios utilizing Mezzi’s recommendations achieved approximately 15% better risk-adjusted returns compared to those built from other investment strategies. Users of the platform, notably millionaires with diverse asset portfolios, typically seek its services for affordable access to investment guidance and ongoing insights on financial health.
Mezzi charges a flat fee for its services, contrasting with the percentage-based fees of traditional financial advisors. This structure appeals to both those looking to replace conventional advisors and DIY investors wanting personalized guidance without relinquishing control over their investments.
While Mezzi does not execute trades or manage assets directly, it facilitates thorough analysis and personalized suggestions based on individual financial data. For users not prepared to fund their investments through a traditional advisor, it provides a flexible alternative to managing their wealth.
As interest in AI-enabled financial services grows, Mezzi sets a foundation for a shift in how individuals approach wealth management.
Why this story matters:
- The rise of AI in personal finance represents a major shift in investment management.
Key takeaway:
- Mezzi combines intelligent AI capabilities with user-friendly interactions to offer personalized financial advice.
Opposing viewpoint:
- Some may prefer traditional advisors for the comfort of human oversight in financial decisions.