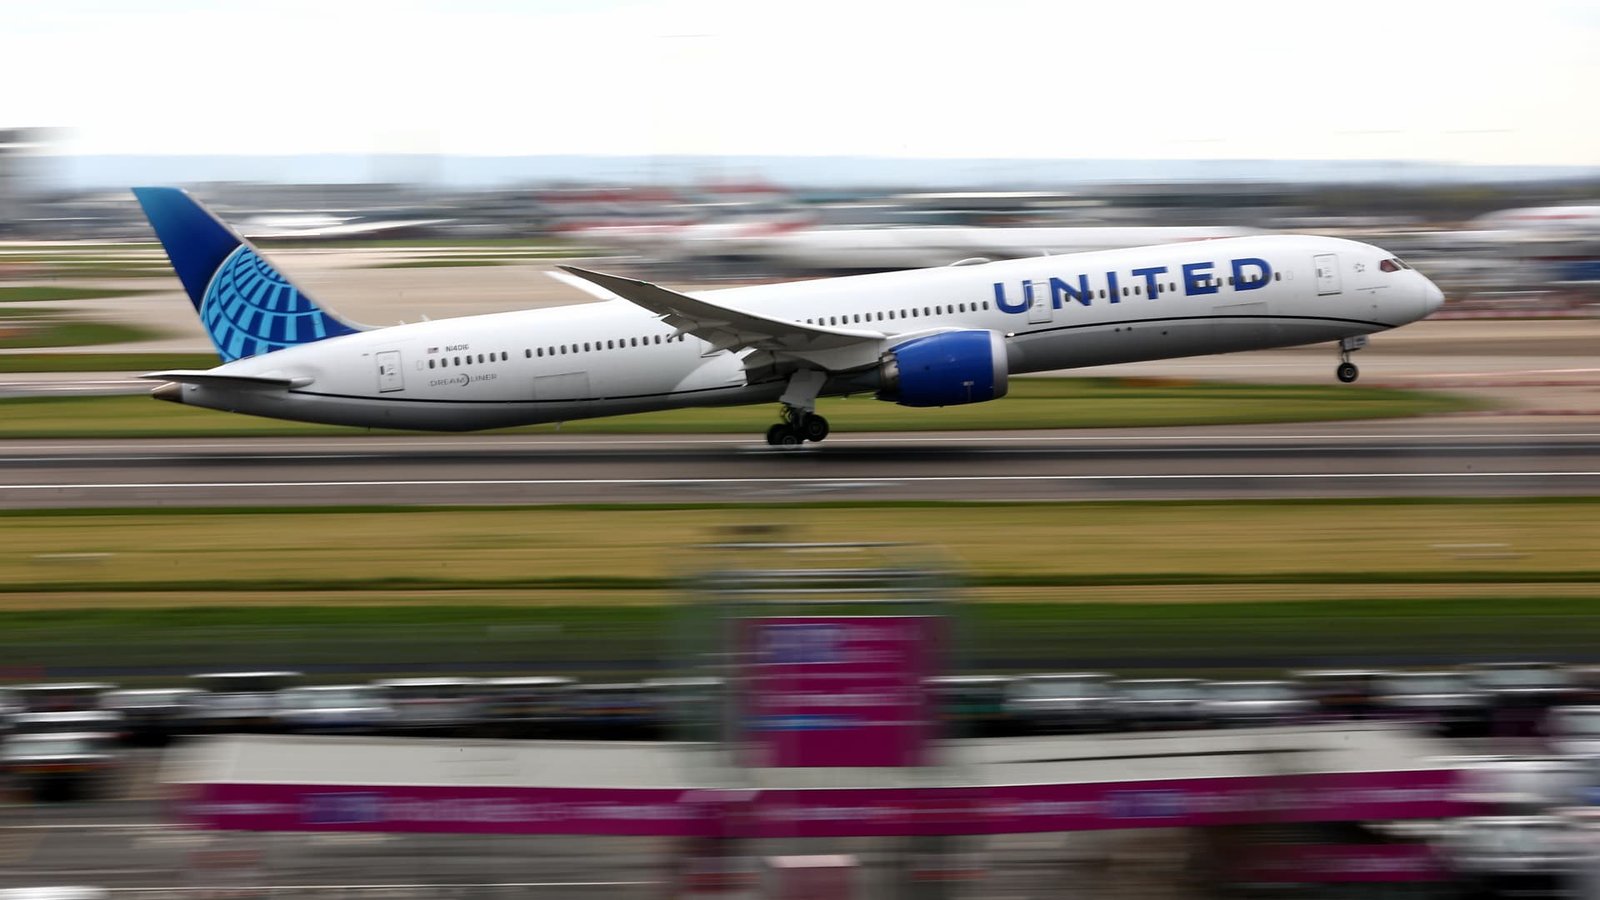
United Airlines has revised its profit projections downward for the year, primarily due to rising fuel costs. On Tuesday, the airline forecasted adjusted earnings of between 50 cents and $1.50 per share for the fourth quarter, significantly lower than the $1.76 forecasted by Wall Street analysts. This revised forecast suggests total adjusted earnings may reach no more than $7.22 per share for 2026, a sharp decline from the previously anticipated annual earnings of $9 to $11 per share.
The airline has been dealing with increasing fuel prices, projecting an average of $4.80 per gallon for the fourth quarter compared to $3.90 in the previous quarter. CEO Scott Kirby mentioned on CNBC that the company is currently passing along about 72% of the elevated fuel costs to consumers, with an aim to increase that figure closer to 100%. High fuel prices have substantially impacted airlines’ operating costs, despite strong demand keeping fare prices elevated.
Regarding recent financial performance, United Airlines reported an 8.5% rise in net income for the third quarter, totaling $1.03 billion or $3.14 per share, compared to $949 million or $2.90 per share in the same period last year. Despite the challenges, revenue increased 17.4% year-over-year to $17.88 billion, and domestic passenger unit revenue rose by 14.5%. The airline continues to see growth, with passenger numbers climbing over 2% compared to last year.
Why this story matters
- It highlights the impact of rising fuel costs on airline profitability and pricing strategies.
Key takeaway
- United Airlines is facing challenges from fuel price increases but reports strong demand as reflected in its customer bookings.
Opposing viewpoint
- Some analysts suggest that the market may not sustain the current level of passenger demand if fares continue to rise significantly.