Bloom Energy reported strong third-quarter financial results, marking a notable year-over-year revenue increase of 138.1%, reaching $1.24 billion, which was nearly 16% above analysts’ expectations. This surge was primarily driven by a substantial rise in product sales and an expansion in service segments. Gross margins saw a significant boost, with adjusted operating margins doubling to over 20%. In response to these favorable results and production trends, the company has raised its revenue guidance for the third consecutive quarter, projecting $4.5 billion for the current fiscal year.
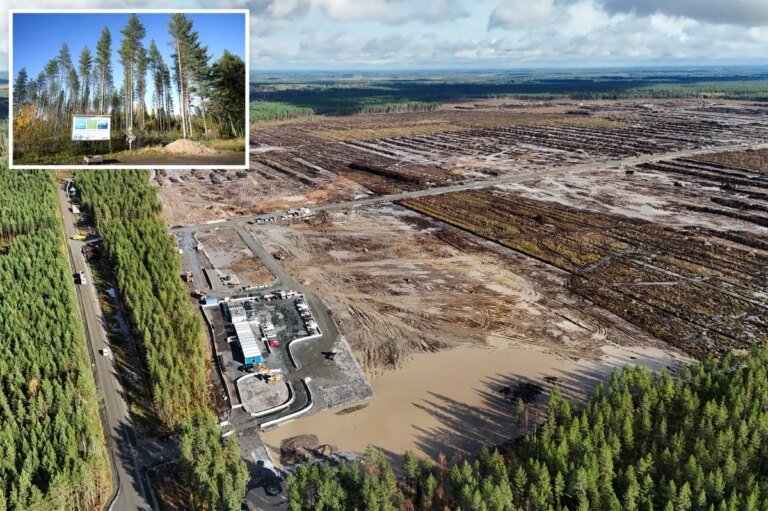
Despite the positive outlook, Bloom Energy faces challenges related to Oracle’s ongoing Project Jupiter in New Mexico, which is experiencing delays due to regulatory hurdles. While the project is crucial, it represents only about 10% of Bloom’s potential deployments. Furthermore, the company has secured a new partnership with American Electric Power for a 702-megawatt project aimed at providing near-zero-emission power to Google’s data centers, reflecting growing acceptance of Bloom’s fuel cell technology.
Analysts maintain a consensus Moderate Buy rating on Bloom Energy, with potential price targets suggesting an average upside of approximately 20%. However, investors should be aware of risks, including stock dilution from share sales used to fund capacity expansion. While current financial health indicators are strong, challenges in execution remain a critical focus for future growth.
Why this story matters
- It highlights Bloom Energy’s robust financial performance and growth potential in the clean energy sector.
Key takeaway
- The company’s revenue outlook is optimistic despite challenges related to the Oracle project and industry risks.
Opposing viewpoint
- Some analysts suggest other stocks may present a better investment opportunity than Bloom Energy at this time.